Most people could not list, from memory alone and without looking around the room, everything sitting in a single closet, let alone every possession spread across an entire home. That gap becomes a real, pressing problem only after a fire, flood, break-in, or other sudden loss, when an insurance adjuster asks for a detailed, itemized accounting of what was damaged or stolen and a household is left trying to reconstruct years of accumulated belongings from memory alone under stressful, emotionally taxing circumstances.
A home inventory list closes that gap well ahead of time, creating a thorough record of belongings, their approximate value, and proof of ownership that makes filing a claim faster, smoother, and far more likely to result in fair reimbursement.
Documenting Your Belongings Room by Room
Working through a home methodically, one room at a time, is the most manageable, least stressful way to build a complete inventory without becoming overwhelmed by the scale of the task. Starting in a single room, finishing it fully, and then moving on to the next room keeps the project from stalling out partway through, which is a common outcome when people try to tackle an entire house all at once in one sitting.
- Living areas: furniture, electronics, artwork, rugs, and decorative items, noting brand, approximate purchase date, and estimated value where known.
- Bedrooms: clothing collections of notable value, jewelry, furniture, and any electronics kept in the room, along with closet contents that are easy to overlook.
- Kitchen: appliances, cookware sets, dishware, and any higher-end small appliances that would be costly to replace as a full set.
- Home office: computers, monitors, printers, and any specialized equipment used for work, freelance projects, or hobbies conducted from home.
- Garage and storage areas: tools, sporting equipment, seasonal decorations, and any items stored that a household might forget about until they are needed.
Working room by room over a weekend, rather than trying to finish everything in a single sitting, produces a more thorough and accurate list, since fatigue tends to cause people to rush through remaining rooms and skip items toward the end of a long session.
A simple template, whether a spreadsheet with columns for item name, room, purchase date, estimated value, and photo reference, or a pre-built home inventory app, keeps the project organized from the first room to the last. Deciding on a consistent format before starting avoids the frustration of realizing halfway through that earlier rooms were documented differently than later ones, which can make the finished list harder to search or hand over to an adjuster in a clear, usable format.
Photos, Videos, and Digital Records
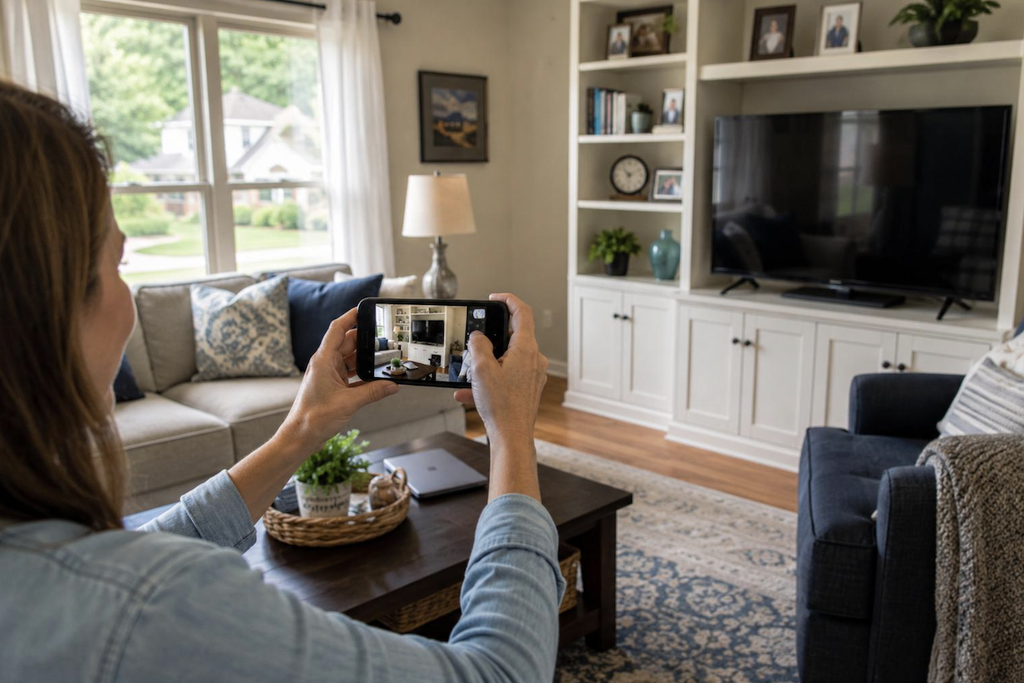
A written list on its own establishes what a household owned, but visual documentation adds a layer of proof that a written description alone cannot fully replace, and the modest extra effort is well worth it. Photos and video walk-throughs capture details a written list might miss, such as the specific model of an appliance or the condition of an item before a loss occurred.
- Wide-angle room photos: capture the overall layout and contents of a room, useful for showing an adjuster the general scope of what was in a space.
- Close-up photos of valuables: serial numbers, brand labels, and any identifying marks on higher-value electronics, jewelry, or collectibles.
- Video walk-through: narrating room by room while filming creates a natural, comprehensive record that is easy to update annually with minimal effort.
- Receipts and purchase confirmations: photographed or saved digitally alongside the corresponding item entry, supporting the claimed value with proof of purchase price.
- Cloud backup: storing photos, videos, and the written list itself in a cloud storage service ensures the record survives even if a phone or computer is damaged in the same event that damaged the home.
Recording a video walk-through while opening drawers, cabinets, and closets provides a level of detail that is easy to skip when relying on photos alone, since many valuable smaller items live tucked away out of sight during a typical wide-angle photo.
Narrating aloud while filming, mentioning brand names, approximate purchase dates, or a rough sense of an item’s value, adds context that a silent video cannot capture on its own. This spoken commentary becomes a useful reference months or years later, when memory of specific details has faded but the recording preserves them exactly as described at the time. Re-recording this walk-through once a year, even a quick five-minute version focused on any new or changed items, keeps the video record aligned with the written list rather than letting the two drift apart over time.
Valuing High-Cost Items Separately
Certain categories of belongings warrant more careful attention than a general room-by-room list provides, both because they carry outsized value and because a standard homeowners or renters policy often caps reimbursement for these categories well below their full worth unless specifically scheduled.
- Jewelry and watches: often subject to a low sub-limit under standard policies, making a separate rider or scheduled endorsement worth exploring for pieces above that threshold.
- Fine art and collectibles: benefit from a professional appraisal, both for accurate valuation and for documentation that holds up during a claims dispute.
- Firearms: frequently capped at a modest combined limit under standard policies, so collectors may need additional coverage matched to the true replacement value.
- Electronics and computer equipment: depreciate quickly, so keeping original receipts helps establish either replacement cost or depreciated cash value depending on the policy terms.
- Musical instruments: often excluded or capped under a standard policy, especially for professional-grade instruments used for income-generating work.
Getting a professional appraisal for a handful of the most valuable items in a home, rather than assuming their value is obvious, protects against both underinsuring an item and disputes over its worth after a loss.
Appraisals for items like fine art, antique furniture, or rare collectibles should be updated periodically as well, since market values for these categories can shift substantially over several years, sometimes rising well beyond the figure recorded at the time of purchase. A ten-year-old appraisal on a piece of art that has since appreciated in value could leave a household underinsured despite having done the work to schedule the item in the first place, so revisiting appraisals every five to seven years, or sooner for categories known to fluctuate quickly, keeps coverage aligned with current market conditions.
Storing Your Inventory Somewhere Safe
An inventory list only helps during a crisis if it survives that same crisis, which means storing it only on a home computer or in a filing cabinet inside the house defeats much of its purpose. A fire or flood that destroys physical belongings can just as easily destroy a paper list or a hard drive stored in the same building.
- Cloud storage services: a straightforward way to keep the inventory accessible from any device after a loss, as long as login credentials are remembered or stored securely elsewhere.
- Email to yourself: attaching the inventory file and photos to an email sent to your own account creates a simple, accessible backup that lives outside the home entirely.
- External hard drive off-site: kept at a workplace, a family member’s home, or a safe deposit box, providing a backup that does not depend on internet access.
- Dedicated home inventory apps: many insurance companies and independent developers offer apps designed specifically for this purpose, often syncing automatically to the cloud as items are added.
- Printed copy in a fireproof safe: a low-tech backup option, useful as a supplement to digital storage rather than a sole method of record-keeping.
Storing at least one copy somewhere entirely separate from the physical home, whether digitally in the cloud or physically at another location, is the single most important habit in this entire process, since a beautifully detailed inventory does no good if it is lost along with everything else.
Sharing access to the stored inventory with a trusted family member or close friend outside the household adds another layer of protection, especially for anyone who lives alone. In the aftermath of a serious event, having a second person who can retrieve the inventory and pass it along to an insurance company or emergency contacts removes one more burden from a household already dealing with a stressful and disorienting situation. This kind of shared access costs nothing beyond a few minutes of setup and can make a real difference during the confusing first days following a major loss.
Updating the List After Major Purchases
A home inventory is not a one-time project; it needs periodic updates to stay accurate as belongings change through purchases, gifts, and items that get sold, donated, or discarded over the years. Without updates, a list slowly drifts out of sync with what a household owns, undermining its usefulness right when it matters most.
- After a major purchase: adding a new appliance, piece of furniture, or electronic device to the list immediately, while receipts and details are still on hand, prevents the task from piling up.
- Annual review: setting a yearly reminder to walk through the home again and confirm the list still reflects current belongings catches items that changed hands throughout the year.
- After a renovation: updating the list to reflect new fixtures, built-in appliances, or structural changes helps ensure the home’s overall coverage amount still matches its current contents and condition.
- Following a move: rebuilding or thoroughly reviewing the list after relocating to a new home catches items that were lost, damaged, or left behind during the move itself.
- Holiday and gift season: a natural time to add newly received electronics, jewelry, or other valuable gifts before they get absorbed into daily life and forgotten.
Tying inventory updates to an existing annual habit, such as reviewing insurance policies at renewal time, makes the update far more likely to happen consistently than treating it as a separate task with no natural trigger.
Setting a recurring calendar reminder tied to a memorable date, such as a birthday, the start of a new year, or the anniversary of moving into a home, gives the task a fixed anchor point rather than relying on remembering to do it whenever there happens to be free time. Some households pair the update with an existing spring cleaning or seasonal decluttering routine, which naturally involves going through closets, storage areas, and rooms that might otherwise be skipped during a quick annual check.
Filing a Claim With Accurate Records
When a loss does occur, a thorough, well-organized inventory transforms what is often a stressful, drawn-out claims process into a more straightforward exchange of information with an adjuster. Claims backed by photos, receipts, and a clear written record tend to move faster and face less pushback than claims relying solely on a policyholder’s memory of what was lost.
Adjusters are trained to evaluate claims based on the evidence presented, and a detailed inventory shifts the burden of proof away from memory and toward documentation that is hard to dispute. This can matter a great deal during a widespread disaster, when adjusters are handling a high volume of claims and have limited time to spend investigating each one individually, making a clear, well-documented claim more likely to be processed quickly and at a fair value.
It is worth noting that most policies offer a choice, or default, between depreciated cash value and replacement cost coverage, and an inventory list supports either calculation, though replacement cost coverage generally results in a higher payout since it does not subtract depreciation from an item’s original value. Reviewing which type of coverage a policy provides, ideally before a loss occurs, clarifies what kind of reimbursement to expect once a claim is filed.
Working with a public adjuster is another option worth knowing about for a large or complex loss, since this professional represents the policyholder’s interests rather than the insurance company’s, for a fee typically taken as a percentage of the final settlement. A well-organized home inventory makes even a self-managed claim far more manageable, but for a substantial loss involving many high-value items or a disputed valuation, bringing in outside help to negotiate with the insurer can be worth the added cost. Keeping copies of every communication with the insurance company, including emails, claim numbers, and the names of adjusters spoken with over the phone, further supports a smooth process regardless of whether a public adjuster is involved.
Final Thoughts
A home inventory list takes an afternoon or two to build and only a few minutes a year to maintain, yet it can make the difference between a smooth insurance claim and a drawn-out dispute after a truly difficult loss. Working room by room, backing up the list with photos and receipts, and storing a copy somewhere safely outside the home are the core habits that make this project worthwhile. Paying special attention to high-value categories like jewelry, art, and electronics ensures those items are properly covered rather than capped under a standard policy limit.
Once built, keeping the list current after major purchases, renovations, or other life changes is a small ongoing task that pays off exactly when it is needed most, turning a stressful, uncertain claims process into a far more manageable one.
Frequently Asked Questions
How often should I update my home inventory list?
An annual review is a reasonable baseline, supplemented by adding major purchases as they happen throughout the year rather than waiting for the yearly update. This keeps the list from falling too far out of date while avoiding the burden of constant maintenance.
Do I need receipts for every item on my inventory list?
Receipts strengthen a claim by establishing purchase price, but they are not strictly required for every item. Photos, the item’s estimated value, and a written description still provide useful documentation even without a receipt for lower-value or older belongings.
Is a home inventory app better than a spreadsheet?
Either approach works, and the better choice depends on personal preference. Apps often offer built-in photo storage and cloud syncing, while a spreadsheet gives more control over formatting and can be just as effective if stored securely with a backup outside the home.
Will a home inventory list speed up my insurance claim?
Yes, in most cases a detailed inventory with photos and receipts allows an adjuster to process a claim more quickly, since much of the documentation an adjuster would otherwise need to request is already prepared and organized in advance.
Should renters create a home inventory list too?
Absolutely, since renters insurance also covers personal belongings, and a thorough inventory is just as useful for a renter’s claim as it is for a homeowner’s. Renters often own less real estate but can still accumulate a substantial amount of personal property worth documenting.
What should I do with my inventory list if I sell a valuable item?
Removing the item from the active list and noting the sale date keeps the inventory accurate, and moving the sold item to an archived section rather than deleting it entirely preserves a record in case questions arise later about its earlier ownership.